Speak with a licensed insurance agent

1-866-316-7339

TTY user 711 Mon-Fri : 8am-9pm EST

Medicare Supplement Plans 2027: Medigap Coverage, Costs & How to Choose

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 1, 2026

Medicare Supplement plans 2027, also called Medigap, help pay the costs Original Medicare leaves behind: deductibles, the 20% you owe on most medical care, and hospital coinsurance. You keep Original Medicare, see any doctor in the U.S. who accepts it, and the Medigap plan pays its share of the bill.

Unlike Medicare Advantage, Medigap benefits are set by federal law. A Plan G from one insurance company covers exactly the same things as a Plan G from another, and the benefits do not change from year to year. What differs is the price, and that is where most of the money is saved or lost.
Medicare Supplement Plans 2027 at a Glance

Plan What you pay besides the premium Best known for
Plan G The Part B deductible ($283 in 2026) The most popular plan for people new to Medicare
Plan N The Part B deductible, copays up to $20 for some office visits and up to $50 for ER visits, and any Part B excess charges A lower premium than Plan G
High-deductible Plan G A yearly deductible ($2,950 in 2026) before the plan pays The lowest premiums
Plan K 50% of most costs until a yearly limit ($8,000 in 2026) Low premium with a cap
Plan L 25% of most costs until a yearly limit ($4,000 in 2026) Middle ground between K and G
Plan F Nothing for covered services Only for people eligible for Medicare before January 1, 2020

The dollar amounts above are 2026 figures. Medicare announces the 2027 Part B deductible, high-deductible Plan G deductible and Plan K and Plan L limits in the fall. Plan benefits stay the same; only those amounts and your premium can change.

Compare 2027 Medicare Supplement plans and enroll online

Speak with a licensed insurance agent

1-866-316-7339TTY 711

Mon-Fri: 8am-9pm ET

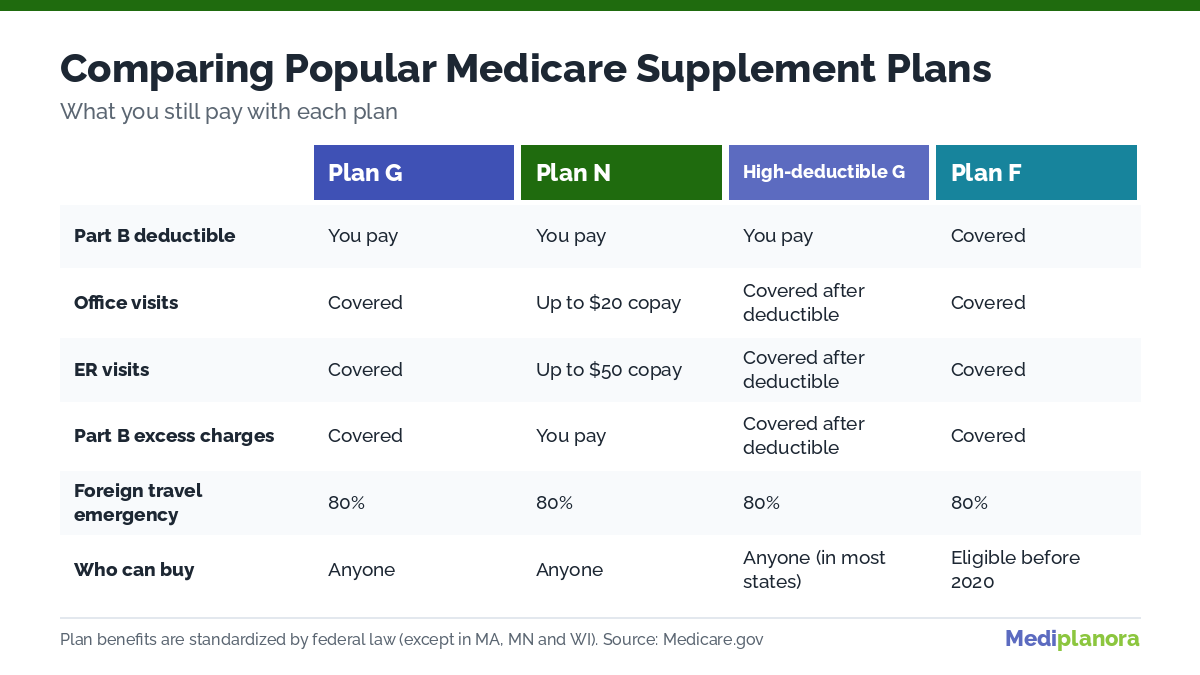
Medicare Supplement plans compared: Plan G, Plan N, high-deductible Plan G and Plan F benefits side by side

What Medicare Supplement Plans Cover

Depending on the plan letter, a Medicare Supplement plan can pay:

  • The Medicare Part A hospital deductible ($1,736 per benefit period in 2026)
  • Part A hospital coinsurance, plus up to 365 extra hospital days after Medicare benefits run out
  • The 20% Part B coinsurance on doctor visits, outpatient care and medical equipment
  • Skilled nursing facility coinsurance and hospice coinsurance
  • The first three pints of blood each year
  • Part B excess charges (Plan G and Plan F)
  • 80% of emergency care when you travel outside the U.S., up to plan limits (Plans C, D, F, G, M and N)

Medigap does not cover prescription drugs, routine dental, vision or hearing care, or long-term care. For prescriptions, most people pair a Medigap plan with a stand-alone Medicare Part D plan.

Comparing the Most Popular Medigap Plans

There are ten standardized Medigap plans, labeled with letters: A, B, C, D, F, G, K, L, M and N. Massachusetts, Minnesota and Wisconsin use their own standardized plans. In practice, most people compare four: Plan G, Plan N, high-deductible Plan G and, if they qualify, Plan F.

Plan C and Plan F are closed to anyone who first became eligible for Medicare on or after January 1, 2020. If you were eligible before that date, you can still buy them, but they usually cost more than Plan G for only one extra benefit: the Part B deductible.

Medigap Plan G vs Plan N 2027 comparison of premiums, copays and excess charges

Plan G vs Plan N in 2027

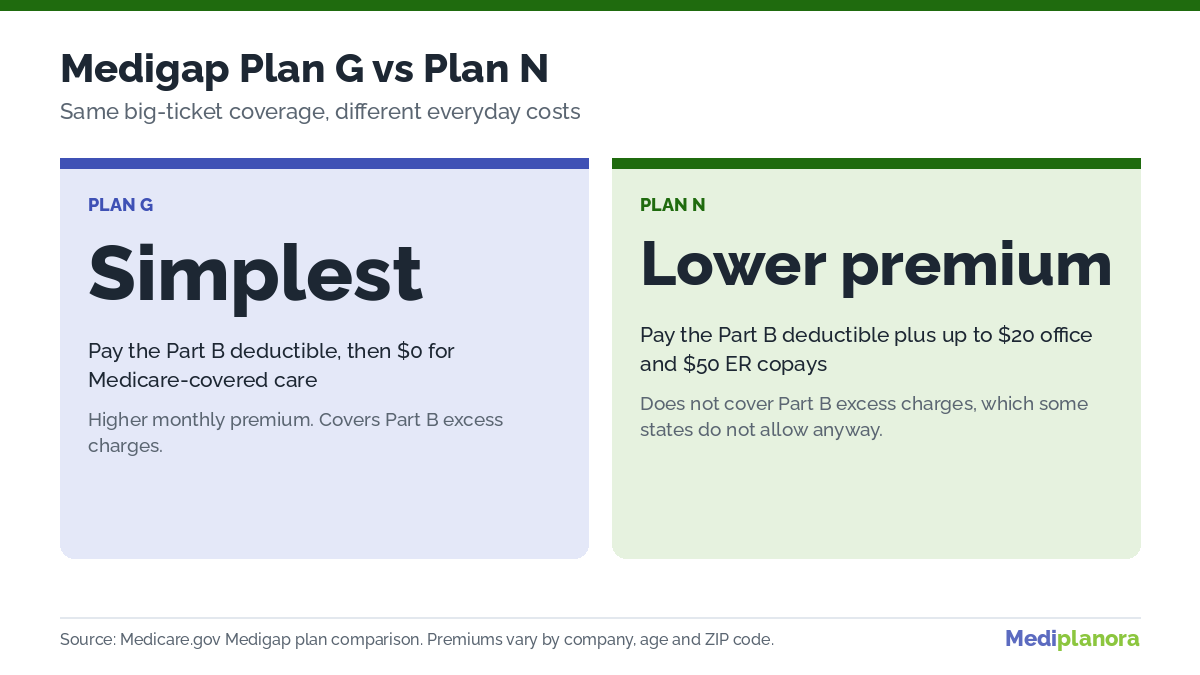
Plan G and Plan N are the two plans most people end up choosing between. Both cover the big costs: hospital stays, the Part A deductible and the 20% Part B coinsurance. The differences are in the small, everyday costs.

PLAN G

After you pay the yearly Part B deductible, Plan G pays your share of all Medicare-covered care. No office copays, no emergency room copays and no excess charges. You pay more each month for that simplicity.

PLAN N

Plan N usually costs less each month. In return you pay up to $20 for some office visits, up to $50 for emergency room visits that do not lead to an admission, and any Part B excess charges.

Excess charges are the extra amount, up to 15% above the Medicare-approved price, that doctors who do not accept Medicare assignment can bill. Most doctors accept assignment, and some states, including New York, Pennsylvania and Ohio, do not allow excess charges at all.

Run the break-even math. If Plan N saves you $30 a month, that is $360 a year. You would need about 18 office copays at $20 to spend that savings. If you see doctors often, Plan G may come out ahead. If you are healthy and rarely see a doctor, Plan N usually wins.

Compare plans & costs in your area

Or speak with a licensed insurance agent

1-866-316-7339TTY 711

Mon-Fri: 8am-9pm ET

What Medicare Supplement Plans Cost

Because the benefits are identical, price is the main difference between companies. Your premium depends on the plan letter, your age, your ZIP code, your sex and whether you use tobacco. Many companies also offer household discounts.

Insurance companies set prices in one of three ways, and it matters over time:

  • Community-rated: everyone pays the same price regardless of age.
  • Issue-age-rated: the price is based on your age when you buy and does not rise because you get older.
  • Attained-age-rated: the price is based on your current age and rises as you get older.

All three types can still increase because of inflation and claims costs. Ask how a company prices its plans and how its rates have changed in recent years, not just what the first-year premium is.

Medigap Open Enrollment Period timeline showing the six-month guaranteed acceptance window after enrolling in Part B at 65

When to Buy: Your Medigap Open Enrollment Period

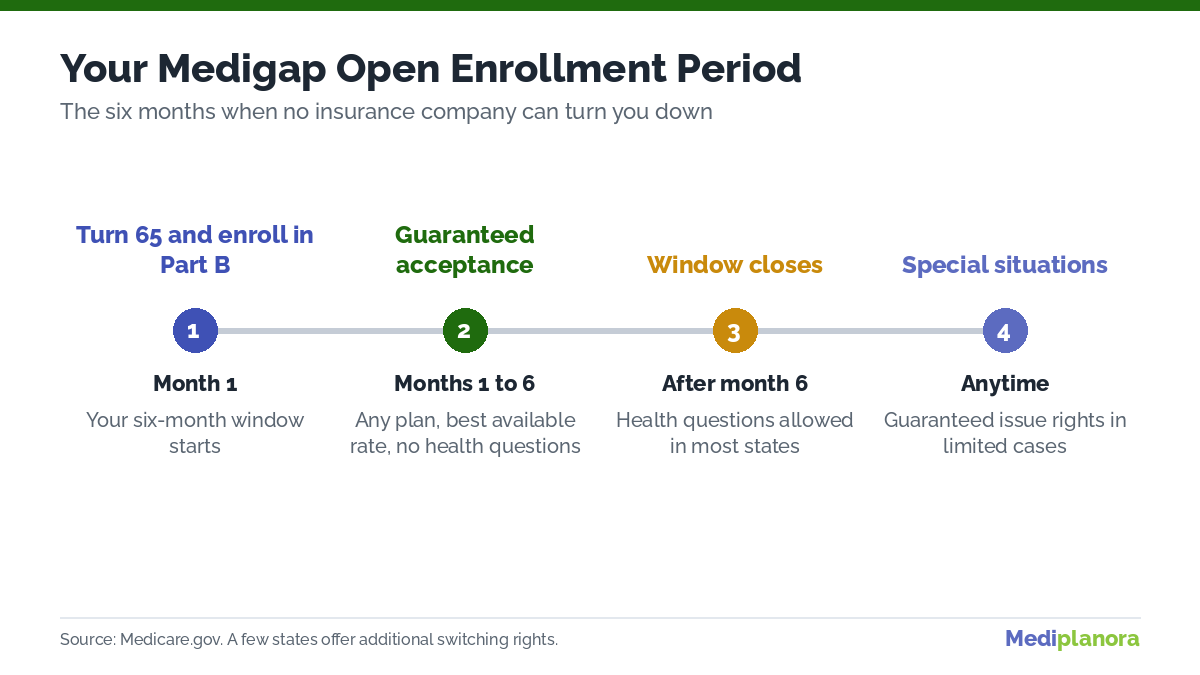
Timing matters more with Medigap than with almost any other Medicare decision. Your Medigap Open Enrollment Period lasts six months and starts the first month you are both 65 or older and enrolled in Part B.

During those six months, an insurance company must sell you any Medigap plan it offers, at its best available rate, no matter your health. After that window closes, insurance companies in most states can ask health questions, charge more or turn you down.

DO NOT MISS THIS WINDOW

If you delay and later develop a health condition, you may not be able to buy the Medigap plan you want. Some people do get guaranteed issue rights later, for example if a Medicare Advantage plan leaves their area or they try Medicare Advantage for the first time and switch back within a year. A handful of states, such as California and Oregon, also give extra chances to switch plans each year.

Medicare Supplement vs Medicare Advantage

A Medicare Supplement plan works alongside Original Medicare. Medicare Advantage plans replace it with a private plan that often has a network, lower premiums and extra benefits.

MEDICARE SUPPLEMENT MAY FIT IF

You want to see any doctor who accepts Medicare, you want predictable costs with few surprise bills, you travel or split time between states, and you are comfortable paying a higher monthly premium.

MEDICARE ADVANTAGE MAY FIT IF

You want low or $0 premiums, you are comfortable using a network, and you like having drug coverage and extras in one plan.

How to Choose a Medicare Supplement Plan for 2027

YOUR MEDIGAP CHECKLIST

Five steps to the right plan

1

Pick your plan letter first. Decide between Plan G, Plan N, high-deductible Plan G or another letter based on how much cost you want to carry.

2

Compare price, not benefits. The same plan letter has the same benefits from every company, so compare premiums for that letter side by side.

3

Ask how the plan is priced. Find out if it is community, issue-age or attained-age rated, and how its rates have changed.

4

Add drug coverage. Choose a stand-alone Part D plan that covers your prescriptions at your pharmacy.

5

Buy during your Medigap Open Enrollment Period. Your six-month window starts when you are 65 and enrolled in Part B. Outside it, health questions may apply.

A Medicare Supplement plan is one of several ways to cover what Original Medicare leaves behind. Mediplanora compares Medigap, Medicare Advantage plans and stand-alone Medicare Part D coverage side by side, so you can see every option in your area before you decide.

View Medigap Plans in your area

Speak with a licensed insurance agent

1-866-316-7339TTY 711

Mon-Fri: 8am-9pm ET

Medicare Supplement Plans 2027 FAQs

➤  What is the best Medicare Supplement plan for 2027?

There is no single best plan for everyone. Plan G is the most popular choice for people new to Medicare because it covers everything Original Medicare leaves behind except the Part B deductible. Plan N usually costs less each month in exchange for some office and emergency room copays. High-deductible Plan G has the lowest premiums but a large deductible. The right plan depends on your budget, your health and how much risk you are comfortable carrying.

➤  Do Medicare Supplement plans change in 2027?

The benefits do not. Medicare Supplement plans are standardized by federal law, so Plan G covers the same things in 2027 as it did in 2026. What can change is your premium, and the dollar amounts tied to Medicare, such as the Part B deductible, the high-deductible Plan G deductible and the Plan K and Plan L out-of-pocket limits, which are updated each year.

➤  How much does a Medicare Supplement plan cost?

It depends on the plan letter, the insurance company, your age, your ZIP code, your sex and whether you use tobacco. Prices for the same plan can vary a lot between companies even though the benefits are identical. You also keep paying your Medicare Part B premium on top of your Medigap premium.

➤  Can I be turned down for a Medicare Supplement plan?

Not during your Medigap Open Enrollment Period, the six months that start when you are 65 or older and enrolled in Part B. During that window an insurance company must sell you any plan it offers at its best available rate, regardless of your health. After that window, insurance companies in most states can ask health questions and decline you unless you have a guaranteed issue right.

➤  Do Medicare Supplement plans cover prescription drugs?

No. Medicare Supplement plans sold today do not include drug coverage. Most people who choose a Medigap plan also join a stand-alone Medicare Part D plan to cover prescriptions.

➤  Is Medigap the same as a Medicare Supplement plan?

Yes. Medigap and Medicare Supplement insurance are two names for the same thing: a private policy that helps pay the costs Original Medicare does not cover, such as deductibles, coinsurance and copays.

Have Questions?

Speak with a licensed insurance agent

1-866-316-7339

TTY users 711

Mon-Fri: 8am-9pm ET

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-866-316-7339TTY 711

Mon-Fri: 8am-9pm ET